Facebook
 X
 Pinterest
 Copy Link
How do I use a VA loan to buy a home near Fort Meade, Maryland?
Who qualifies for a VA home loan?
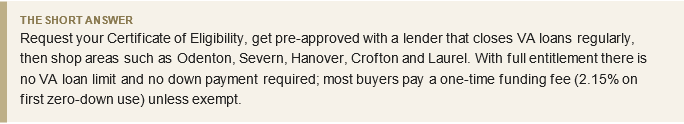
VA-backed purchase loans are available to eligible active-duty service members, veterans, National Guard and Reserve members, and certain surviving spouses. Your first step is the Certificate of Eligibility (COE), which most lenders can pull for you quickly through the VA system.
The COE shows your entitlement. With full entitlement (you have never used the benefit, or you used it and sold the home), the VA does not cap your loan amount. You still need to qualify on income, debts and VA’s
residual-income test. With partial entitlement – for example, you still own a home with a VA loan elsewhere – county loan limits come into play and a down payment may be needed.
What does a VA loan cost in 2026?
There is no monthly mortgage insurance on a VA loan. Instead, most buyers pay a one-time VA funding fee, which can usually be rolled into the loan.
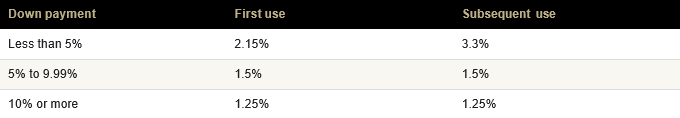
On a $400,000 first-use, zero-down loan, the fee is $8,600. Veterans receiving VA disability compensation, eligible surviving spouses and active-duty Purple Heart recipients are generally exempt. If a disability claim is still pending at closing, ask your lender about a refund if the rating is later made retroactive.
Which areas near Fort Meade do buyers look at?
Fort Meade sits in western Anne Arundel County, between Baltimore and Washington, with access from MD-175, MD-32, MD-198, the Baltimore-Washington Parkway (MD-295) and I-95. Areas buyers commonly consider include:
- Odenton (Anne Arundel) – closest to the Reece Road main gate, with MARC Penn Line
- Severn and Hanover (Anne Arundel) – east and north of post, near the MD-32 gates, with a mix of resale and newer homes.
- Crofton and Gambrills (Anne Arundel) – via MD-3 and MD-
- Laurel and Maryland City – straddling Anne Arundel and Prince George’s counties; check which county an address is in, because property tax rates differ.
- Columbia and Jessup (Howard County) – north and west via MD-
Choose by commute, budget and home features. Gate hours and traffic patterns vary, so test-drive your commute at the time you would actually travel.
Can I buy a condo or townhome with a VA loan?
Yes. Townhomes on fee-simple lots are treated like single-family homes. A condominium must be on the VA’s approved condo list, so check the project before you write an offer. Your agent and lender can confirm status quickly.
How do VA appraisals and offers work?
A VA appraiser checks value and the VA’s Minimum Property Requirements (safe, sound and sanitary). Items like peeling paint on older homes, missing handrails or a failing roof may have to be repaired before closing. To keep your offer strong:
- Submit a full pre-approval, not just a pre-
- Ask the listing agent about known repair items up
- Offer a settlement date that matches your PCS or transition
- Sellers may help with closing costs; VA sets limits on certain concessions, and your lender will explain the rules for your file.
What closing costs should VA buyers in Anne Arundel County budget for?
A zero-down VA loan does not mean zero cash. Plan for an earnest money deposit, a home inspection, lender and title charges, and prepaid taxes and insurance. Maryland also charges recordation and transfer taxes. In Anne Arundel County, recordation is 0.7% and the county transfer tax is 1.0% (1.5% at $1 million or more), on top of the 0.5% state transfer tax. Who pays which share is set by your contract, but a first-time Maryland buyer who will live in the home gets a reduced 0.25% state rate that the seller must pay. Your title company will show exact figures on your Closing Disclosure.
Are there Maryland benefits that stack with a VA loan?
- Disabled-veteran property tax exemption: veterans rated 100% permanent and total service-connected disabled (and certain surviving spouses) may be exempt from real property tax on their principal residence. Apply through the Maryland State Department of Assessments and Taxation (SDAT), ideally before closing so your escrow is set correctly.
- County veteran credits: Anne Arundel County offers additional property tax credits for certain veterans; check with the county Office of Finance.
- Homestead Tax Credit: any owner-occupant should file with SDAT to cap annual assessment
- Maryland Mortgage Program (MMP): offers VA-eligible loan options through approved lenders, with down payment and closing cost assistance for those who qualify.
What does the step-by-step process look like?
- Request your COE and gather your DD-214 or statement of
- Get pre-approved with a lender experienced in VA
- Set your search with an agent who knows the Fort Meade
- Write the offer, order the inspection, then the VA
- Complete any required repairs, clear conditions and settle with a Maryland title
Frequently asked questions
Is there a VA loan limit in Anne Arundel County in 2026?
Not if you have full entitlement. The VA removed loan limits for borrowers with full entitlement in 2020. County limits matter only with partial entitlement, such as when an existing VA loan is still outstanding.
Do I need a down payment for a VA loan near Fort Meade?
No. Eligible borrowers can buy with zero down. Putting 5% or more down lowers the first-use funding fee from 2.15% to 1.5%.
Who is exempt from the VA funding fee?
Veterans receiving VA compensation for a service-connected disability, eligible surviving spouses, and active-duty service members awarded the Purple Heart are generally exempt. Your COE shows your status.
What are transfer and recordation taxes in Anne Arundel County?
Recordation is 0.7% and county transfer tax is 1.0% (1.5% at $1 million or more), plus the 0.5% Maryland transfer tax. First-time Maryland buyers get a reduced 0.25% state rate, paid by the seller.
Can I use a VA loan more than once?
Yes. You can reuse the benefit after selling a home and restoring entitlement, and in some cases keep one VA loan while buying another with remaining entitlement. Subsequent zero-down use carries a 3.3% funding fee.

Sources
- S. Department of Veterans Affairs – VA home loans: https://www.va.gov/housing-assistance/home-loans/
- LRG Realty – VA Funding Fee in 2026: Rates, Charts, Exemptions:
https://lrgrealty.com/lrg-blog/va-funding-fee-2026-rates-exemptions/
- Gordon Feinblatt – Recordation and Transfer Tax Rates in Maryland Explained (Oct. 2026): https://www.gfrlaw.com/what-we-do/insights/recordation-and-transfer-tax-rates-maryland-explained
- PCS Pay It Forward – Buying a Home Near Fort Meade: https://pcspayitforward.com/buying-a-home-near-fort-meade/
- VA Loan Network – Maryland VA Loans 2026: https://valoannetwork.com/va-loan-guides/maryland/
- Maryland Mortgage Program – DHCD: https://mmp.maryland.gov/
Program terms, rates and limits change. Information current as of October 29, 2026; confirm details with the agency or your lender. This article is general information, not legal, tax or lending advice.
About the author: Reggie Butler
Broker/Owner, CENTURY 21 ENVISION
Reggie Butler leads CENTURY 21 ENVISION in Bowie, Maryland, helping buyers, sellers, investors and business owners across Washington DC, Maryland and Northern Virginia with residential sales and commercial leasing and acquisitions.
1318 Crain Hwy, Bowie, MD 20716 · 240-232-7005 · 240-938-1244